Ioannis PapantonisEconomist & Quantitative Researcher

Ioannis Papantonis

Economist & Quantitative Researcher

Based in London, I’m a Manager and Technical Modelling Specialist at the Bank of England, where I develop statistical models and simulation tools to assess financial risks to the Bank’s balance sheet. My work also includes evaluating fixed-income portfolio strategies and understanding how they perform under stress.

Alongside my role at the Bank, I’m a Postdoctoral Researcher at Athens University of Economics and Business. My research focuses primarily on volatility modelling and forecasting using high-frequency data, with broader interests in financial econometrics, asset pricing, derivatives, portfolio theory and risk management.

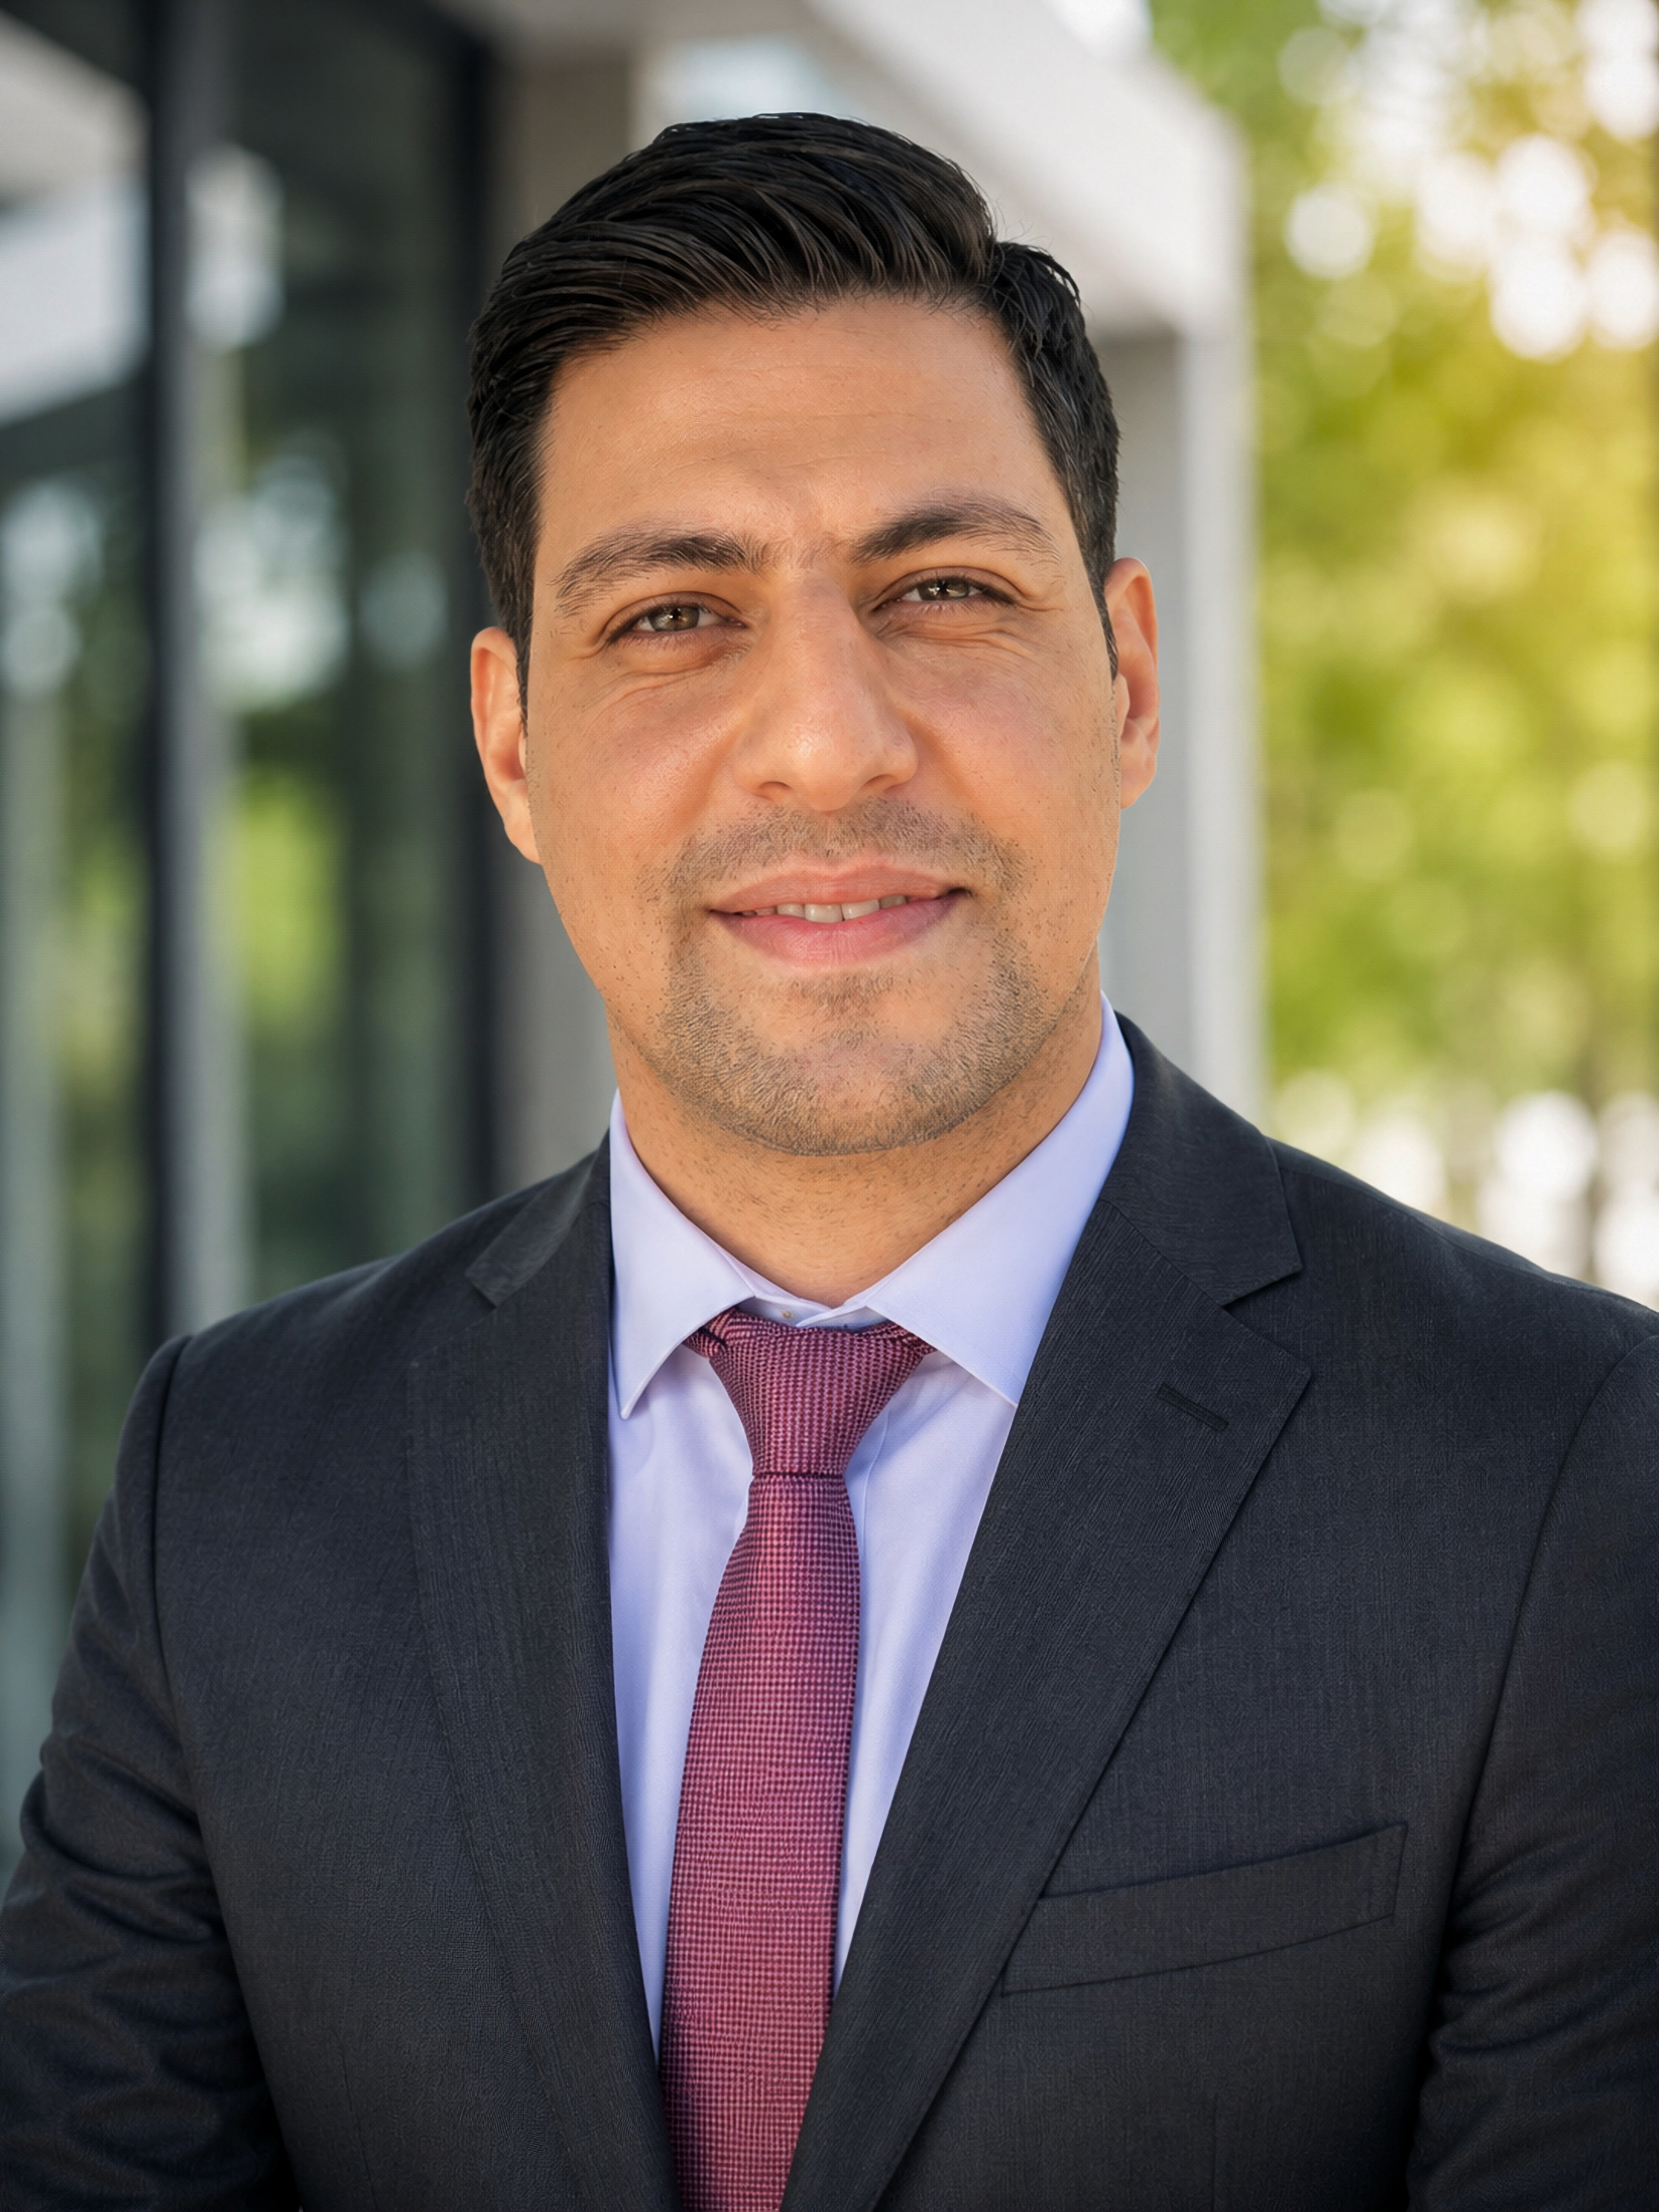
Portrait of Ioannis Papantonis

Experience & Education.

Professional Experience

Bank of England

London · Apr 2016–present

Manager | Technical Modelling Specialist

Jul 2022 – present

Financial Risk Management Division | Quantitative Risk Analytics

Provide technical expertise for the development of statistical models supporting the Bank of England’s first-line risk-management function. Lead the development of a back-testing methodology for the asset-allocation strategy used to manage the Exchange Equalisation Account (EEA) portfolio on behalf of HM Treasury.

Senior Quantitative Analyst

May 2019 – Jul 2022

Financial Risk & Resilience Division | Risk Methodology Team

Implemented and back-tested Exposure at Default and Expected Shortfall models for sovereign bonds, equities and derivatives; challenged and validated risk and asset-allocation models developed in other areas of the Bank.

Quantitative Risk Analyst

Apr 2016 – May 2019

Financial Risk & Resilience Division | Risk Methodology Team

Designed and developed methodologies to evaluate and manage financial risks to the Bank’s balance sheet across asset classes and liquidity operations.

Research Experience

Athens University of Economics and Business

Athens, Greece · Apr 2024–present

Postdoctoral Researcher in Economics

Apr 2024 – present

Financial econometrics with large datasets and high-frequency data, with a focus on volatility modelling in financial markets.

Explore my research ↗

Education

PhD in Economics

Oct 2015 – May 2022

Athens University of Economics and Business (AUEB), Greece

Essays on Modelling and Forecasting Stock Market Volatility

MSc in Finance

Sep 2009 – Sep 2010

Warwick Business School (WBS), United Kingdom

Thesis: Cointegration-Based Trading Strategies

BSc in Economics

Sep 2004 – Jan 2009

Aristotle University of Thessaloniki (AUTH), Greece

GPA: 9.4/10 – Graduated 1st with Honors

Research.

Published Papers

2023
Improving Variance Forecasts: The Role of Realized Variance Features

with Leonidas Rompolis and Elias Tzavalis

International Journal of Forecasting

Abstract

In this paper, we effectively extend the Realized-EGARCH (R-EGARCH) framework by allowing the conditional variance process to incorporate exogenous variates related to different observable features of Realized Variance (RV). The choice of these features is well motivated by recent studies on the Heterogeneous Autoregressive (HAR) class of models. We examine several specifications nested within our augmented R-EGARCH representation, and we find that they perform significantly better than the standard R-EGARCH model. These specifications incorporate realized semi-variances, heterogeneous long-memory effects of RV, and jump variation. We also show that the performance of our framework further improves if we allow for skewness and excess kurtosis for asset return innovations, instead of assuming normality. This can better filter the true distribution of the return innovations, and thus can more accurately estimate their effects on the variance process. This is also supported by a Monte Carlo simulation exercise executed in the paper.

2023
Augmenting the Realized-GARCH: The Role of Signed-Jumps, Attenuation-Biases and Long-Memory Effects

with Orestis Agapitos, Leonidas Rompolis and Elias Tzavalis

Studies in Nonlinear Dynamics & Econometrics

Abstract

This paper extends the Realized-GARCH framework, by allowing the conditional variance equation to incorporate exogenous variables related to intra-day realized measures. The choice of these measures is motivated by the so-called heterogeneous auto-regressive (HAR) class of models. Our augmented model is found to outperform both the Realized-GARCH and the various HAR models in terms of in-sample fitting and out-of-sample forecasting accuracy. The new model specification is examined under alternative parametric density assumptions for the return innovations. Non-normality seems to be very important for filtering the return innovations to which variance responds and helps significantly upon the prediction performance of the suggested model.

2016
Volatility Risk Premium Implications of GARCH Option Pricing Models

Economic Modelling

Abstract

In this paper we explore important implications of capturing volatility risk premium (VRP) within a parametric GARCH setting. We study the transmission mechanism of shocks from returns to risk-neutral volatility by providing an examination of the news-impact curves and impulse–response functions of risk-neutral volatility, in order to better understand how option prices respond to return innovations. We report a value of −3% for the magnitude of the average VRP and we recover the empirical densities under physical and risk-neutral measures. Allowing for VRP is crucial for adding flexibility to the shape of the two distributions. In our estimation procedure, we adopt a MLE approach that incorporates both physical return and risk-neutral VIX dynamics. By introducing volatility - instead of variance - innovations in the joint likelihood function and by allowing for contemporaneous correlation between innovations in returns and the VIX we show that we may critically reduce the bias and improve the efficiency of the joint maximum likelihood estimator, especially for the parameters of the volatility process. Modeling returns and the VIX as a bi-variate normal permits identification of a contemporaneous correlation coefficient of approximately −30% between returns and risk-neutral volatility.

2016
Cointegration-Based Trading: Evidence on Index Tracking & Market-Neutral Strategies

Managerial Finance

Abstract

Purpose

The purpose of this paper is to present an alternative approach to equity trading that is based on cointegration. If there are long-run equilibria among financial assets, a cointegration-based trading strategy can exploit profitable opportunities by capturing mean-reverting short-run deviations.

Design/methodology/approach

First, the author introduces an equity indexing technique to form cointegration tracking portfolios that are able to replicate an index effectively. The author later enhances this tracking methodology in order to construct more complex portfolio-trading strategies that can be approximately market neutral. The author monitors the performance of a wide range of trading strategies under different specifications, and conducts an in-depth sensitivity analysis of the factors that affect the optimal portfolio construction. Several statistical-arbitrage tests are also carried out in order to examine whether the profitability of the cointegration-based trading strategies could indicate a market inefficiency.

Findings

The author shows that under certain parameter specifications, an efficient tracking portfolio is able to produce similar patterns in terms of returns and volatility with the market. The author also finds that a successful long-short strategy of two cointegration portfolios can yield an annualized return of more than 8 percent, outperforming the benchmark and also demonstrating insignificant correlation with the market. Even though some cointegration-based pairs-trading strategies can consistently generate significant cumulative profits, yet they do not seem to converge to risk-less arbitrages, and thus the hypothesis of market efficiency cannot be rejected.

Originality/value

The primary contribution of the research lies within the detailed analysis of the factors that affect the tracking-portfolio performance, thus revealing the optimal conditions that can lead to enhanced returns. Results indicate that cointegration can provide the means to successfully reproducing the risk-return profile of a benchmark and to implementing market-neutral strategies with consistent profitability. By testing for statistical arbitrage, the author also provides new evidence regarding the connection between the profit accumulation of cointegration-based pairs-trading strategies and market efficiency.

2014
Jointly Estimating Jump Betas

with Vassilis Polimenis

Journal of Risk Finance

Abstract

Purpose

This paper aims to enhance a co-skew-based risk measurement methodology initially introduced in Polimenis, by extending it for the joint estimation of the jump betas for two stocks.

Design/methodology/approach

The authors introduce the possibility of idiosyncratic jumps and analyze the robustness of the estimated sensitivities when two stocks are jointly fit to the same set of latent jump factors. When individual stock skews substantially differ from those of the market, the requirement that the individual skew is exactly matched is placing a strain on the single stock estimation system.

Findings

The authors argue that, once the authors relax this restrictive requirement in an enhanced joint framework, the system calibrates to a more robust solution in terms of uncovering the true magnitude of the latent parameters of the model, at the same time revealing information about the level of idiosyncratic skews in individual stock return distributions.

Research limitations/implications

Allowing for idiosyncratic skews relaxes the demands placed on the estimation system and hence improves its explanatory power by focusing on matching systematic skew that is more informational. Furthermore, allowing for stock-specific jumps that are not related to the market is a realistic assumption. There is now evidence that idiosyncratic risks are priced as well, and this has been a major drawback and criticism in using CAPM to assess risk premia.

Practical implications

Since jumps in stock prices incorporate the most valuable information, then quantifying a stock's exposure to jump events can have important practical implications for financial risk management, portfolio construction and option pricing.

Originality/value

This approach boosts the “signal-to-noise” ratio by utilizing co-skew moments, so that the diffusive component is filtered out through higher-order cumulants. Without making any distributional assumptions, the authors are able not only to capture the asymmetric sensitivity of a stock to latent upward and downward systematic jump risks, but also to uncover the magnitude of idiosyncratic stock skewness. Since cumulants in a Levy process evolve linearly in time, this approach is horizon independent and hence can be deployed at all frequencies.
Working Papers

2026

Monitoring the Composition of Yield Curve Tail Risk: A Factor-level Control Chart for the Term Structure

with K. Bisiotis

2025

Monetary Policy Announcements & Market Disagreement

with Marco Almbauer

2023

Long-run and Short-run Volatility Dynamics for VIX Derivatives Pricing: Decomposing the Realized-EGARCH

with Leonidas Rompolis and Elias Tzavalis

2023

Financial Leverage, Volatility Feedback and the Impact of Jumps

with Orestis Agapitos, Leonidas Rompolis and Elias Tzavalis

Revise & resubmit

Conference Proceedings

2019

The Impact of Signed-Jump Variation on Forecasting Realized Variance

with E. Tzavalis and L. Rompolis.

Proceedings of the International Conference on Time-Series and Forecasting.

2015

GARCH option-valuation models under non-monotonic pricing kernels: Evidence from Joint Likelihood Estimations

Proceedings of the 22nd Multinational Finance Society Meeting.

2013

On the joint estimation of information betas

Proceedings of the 26th Conference in Statistics, Greek Statistical Institute.

Talks & Conferences.

Invited Talks & Seminars

  • May 2026
    Foreign Exchange Reserve Portfolio Management — Strategic Asset Allocation (SAA)

    Panel discussion with Mike McMorrow (BIS), hosted by the Federal Reserve Bank of New York

  • Mar 2026
    AI in Risk Assessment and Mitigation

    ICMS, Bayes Centre, University of Edinburgh

  • May 2017
    Analytical Tools for Financial Risk Management & Supervision

    CCBS, Bank of England

Conference Presentations

  • Aug 2026
    Vienna–Copenhagen Conference on Financial Econometrics, Vienna, Austria (VieCo)
  • Apr 2026
    10th International Conference on Applied Macro and Empirical Finance (AMEF)
  • Apr 2024
    8th International Conference on Applied Macro and Empirical Finance (AMEF)
  • May 2022
    RCEA Conference on Recent Developments in Economics, Econometrics and Finance
  • Apr 2022
    6th International Conference on Applied Macro and Empirical Finance (AMEF)
  • Jul 2021
    International Conference on Time Series and Forecasting (ITISE 2021)
  • Jun 2021
    7th RCEA Time-Series Workshop, Rimini Centre for Economic Analysis, Uni of Milano-Bicocca
  • Dec 2020
    14th International Conference on Computational & Financial Econometrics, King's College London
  • Sep 2019
    International Conference on Time Series and Forecasting (ITISE 2019)
  • Apr 2016
    2nd International Conference on Applied Macro and Empirical Finance (AMEF)
  • Jun 2015
    2nd Annual Conference of the International Association of Applied Econometrics (IAAE)
  • Jun 2015
    22nd Annual Multinational Finance Society Conference (MFS)
  • Jun 2015
    2015 Spring School of the Society of Financial Econometrics (SoFiE)
  • Jun 2015
    3rd International PhD Meeting in Economics, University of Macedonia
  • May 2015
    1st International Conference on Applied Macro and Empirical Finance (AMEF)
  • Apr 2015
    2015 Spring Conference of the Multinational Finance Society (MFS)
  • Dec 2013
    12th International Conference of the Hellenic Finance & Accounting Association (HFAA)
  • Jul 2013
    1st International PhD Meeting in Economics, University of Macedonia
  • May 2013
    26th Pan-Hellenic Statistics Conference, Greek Statistical Institute (GSI)
  • Apr 2013
    International Conference in Economics and Business, Onassis Foundation

Activities & Awards.

Grants & Awards
  • 2019
    European Social Fund (ESF): Research Grant through the Operational Programme “Human Resources Development, Education and Lifelong Learning” financed by the European Union.
  • 2015
    Multinational Finance Society (MFS): “Best Doctoral Paper Award”, 22nd MFS conference.
  • 2013
    Greek Statistical Institute: Selected for the “Best Young Statistician” award.
  • 2011
    Alexander S. Onassis Public Benefit Foundation: “Scholarship for Doctoral Research”.
  • 2009
    Warwick Business School: “Scholarship for the MSc Finance 2009–2010 programme”.
  • 2005
    State Scholarship Foundation (IKY): “Distinction for academic achievements and morality”.
  • 2004
    Aristotle University of Thessaloniki: “Merit of Success”, Department of Economics exams.
Professional Development
  • May 2026
    Foreign Exchange Reserve Portfolio Management

    Federal Reserve Bank of New York, New York

  • Aug 2025
    Strategic Asset Allocation

    Bank for International Settlements (BIS), hosted in Davos

  • Sep 2024
    Forecasting Macroeconomic & Financial Risk

    Society for Financial Econometrics (SoFiE) and the National Bank of Belgium (NBB), prof. Domenico Giannone and Francesco Furno

  • Jun 2023
    Monetary Policy and the Yield Curve

    Society for Financial Econometrics (SoFiE) and the National Bank of Belgium (NBB), with prof. Glenn Rudebusch and prof. Michael Bauer

  • Jul 2019
    Advanced Summer School in Economics and Econometrics (ASSEE)

    prof. Bruce E. Hansen

  • Aug 2017
    Advanced Risk & Portfolio Management (ARPM) Bootcamp (NYC)

    with prof. Attilio Meucci

  • Jun 2015
    From GARCH and Stochastic Volatility to Realized Volatility and Options

    prof. Torben G. Andersen, University of Coimbra, Portugal

  • Jun 2015
    Society for Financial Econometrics (SoFiE) 2015 Spring School

    National Bank of Belgium (NBB) and CORE Institute (UCL), prof. Eric Renault & prof. Patrick Gagliardini

  • Jul 2013
    10th Summer School in Stochastic Finance

    Athens University of Economics and Business

  • Jun 2012
    5th Annual Conference of the Society for Financial Econometrics (SoFiE)

    Oxford-Man Institute, Said Business School, University of Oxford

  • Jul 2011
    8th Summer School in Stochastic Finance

    Athens University of Economics and Business

Teaching Experience
  • 2012–2015
    PhD Candidate & Teaching Assistant

    Aristotle University of Thessaloniki, School of Economics

    Modules: Advanced Financial Analysis, Portfolio Theory, Business Economics, Derivatives.

  • 2007–2012
    Private tutoring

    Finance modules for undergraduate and postgraduate students.

Journal Refereeing

Studies in Nonlinear Dynamics & Econometrics | Economic Modelling | Finance Research Letters | Business and Economics Journal | Global Economics Journal

Technical Skills
MATLABPython (Pandas, NumPy)RVS-CodeSQLEViewsStataS+GitLaTeX

Beyond Work.

I enjoy exploring new places, whether on foot, by bike or through the lens of a camera.

I play guitar, bass and piano, and have enjoyed performing with bands and orchestras over the years, as well as taking part in national and international music competitions.

In photography, I’m particularly drawn to street scenes and everyday moments. I also enjoy keeping active through running, basketball, swimming and sailing.

Contact.